Claiming Social Security at 62 vs. 70: What Every Age In Between Actually Pays
Claiming Social Security at 62 vs. 70: What Every Age In Between Actually Pays
Social Security is one of the most important financial decisions of your retirement — and it's permanent. Once you choose your claiming age, you live with that payment for the rest of your life.
Most people choose based on a gut feeling or a rough rule of thumb. Here's what the math actually shows.
How the Numbers Work
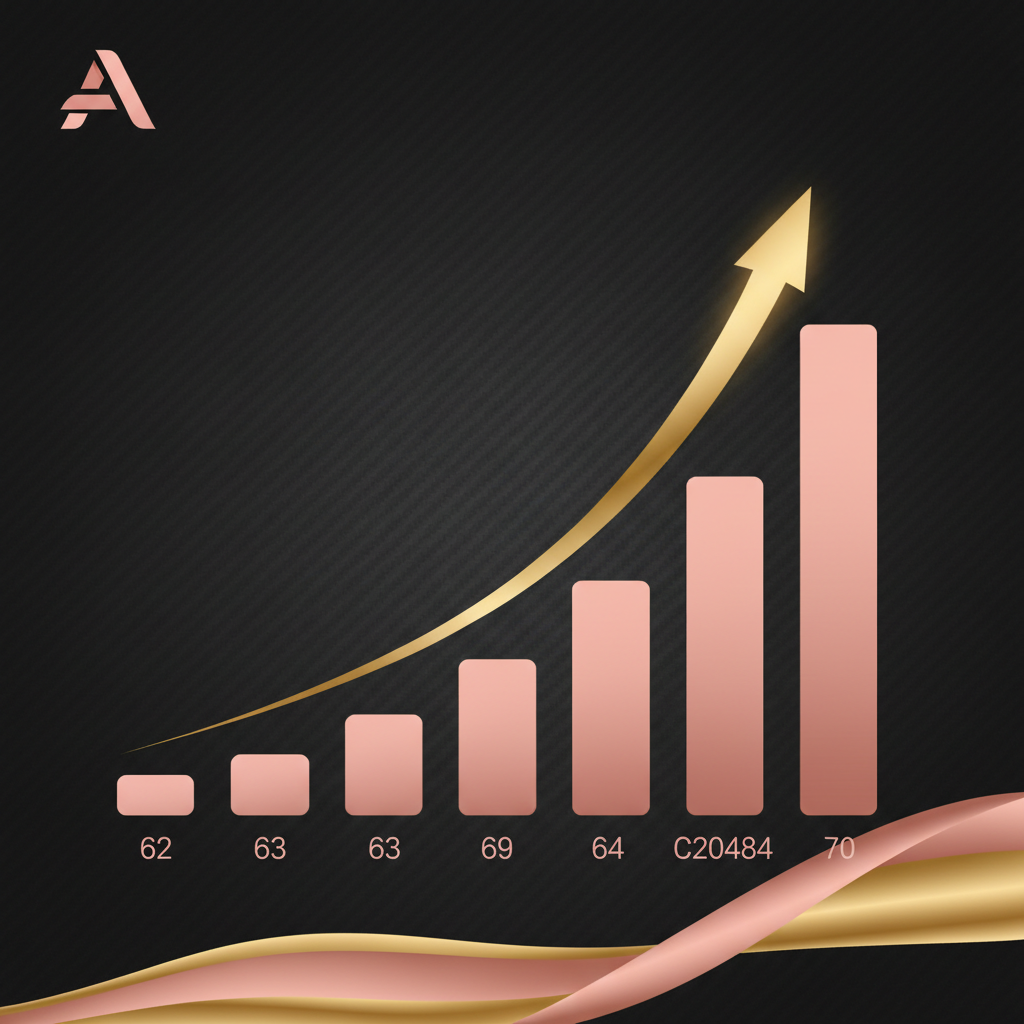
For someone with a Full Retirement Age (FRA) of 67 and an FRA benefit of $2,200/month, here's what each claiming age pays:
| Claiming Age | Adjustment | Monthly Benefit |
|---|---|---|
| 62 | 30% cut | $1,540/mo |
| 63 | 25% cut | $1,650/mo |
| 64 | 20% cut | $1,760/mo |
| 65 | 13.3% cut | $1,907/mo |
| 66 | 6.7% cut | $2,053/mo |
| 67 (FRA) | Full benefit | $2,200/mo |
| 68 | +8% | $2,376/mo |
| 69 | +16% | $2,552/mo |
| 70 | +24% | $2,728/mo |
Difference between 62 and 70, for life: +$1,188/month
What's the "Break-Even" Point?
If you claim at 62 versus waiting until 70, you collect more months of payments early — but each check is $1,188 smaller for life.
The break-even point is typically around age 80–82. If you live longer than that, delaying to 70 pays more in total lifetime benefits. If you pass before that, you would have received more total benefits by claiming early.
But this break-even analysis is only half the picture.
The Factor That Outlives You
For married couples, the higher earner's claiming age determines the survivor benefit — the amount the surviving spouse receives after one partner dies.
If the higher earner claims at 62 and receives $1,540/month, the survivor inherits that lower amount for life. If they delay to 70 and receive $2,728/month, the survivor inherits that amount.
The decision isn't just about your own longevity — it's about the income your spouse will live on as a widow or widower, potentially for decades.
Factors That Should Influence Your Decision
Reasons to claim earlier (62–65):
- Health concerns that reduce your life expectancy
- You need the income immediately
- You have a pension that won't be affected by Social Security timing
- Your spouse is the higher earner and will delay
Reasons to delay (66–70):
- You're in good health and have family longevity
- You have other income sources to bridge the gap
- You're married and your spouse would benefit from a larger survivor benefit
- You want to reduce the risk of outliving your money
The 2032 Social Security Cliff
One factor that often gets left out of this conversation: The 2026 Trustees Report projects the Social Security retirement trust fund runs short in the fourth quarter of 2032. When it does, benefits drop to roughly 78 cents on the promised dollar — a 22% cut, automatically. And analysis built on the Chief Actuary's own projections puts the cut for people retiring just after insolvency at 24% — about $500 a month for the typical retiree. Congress may act before then — or they may not.
This doesn't mean Social Security disappears. It means there's a risk of a 22% benefit reduction for everyone regardless of claiming age. Some financial planners argue this makes claiming earlier more attractive. Others point out that even a reduced benefit at 70 is larger than a full benefit at 62 for most people.
Scott's view: the 2032 cliff is a real planning risk, and it should be part of every Social Security conversation — not ignored.
Want to Know More? Here's the Truth.
Social Security claiming strategy is one of the most complex, most permanent financial decisions in retirement — and it interacts with Roth conversions, Medicare costs, RMDs, taxes on Social Security benefits, and your spouse's benefit in ways that most advisors don't model together.
Scott Borhauer builds comprehensive Social Security claiming models that account for your full financial picture — your IRA balance, your spouse's benefit, your health, your tax situation, and the 2032 risk — so you make this decision with complete information.
Not individualized financial advice. Social Security rules are complex and change frequently. Consult SSA.gov or a qualified Social Security specialist for guidance specific to your situation.
About the Author
Scott Borhauer
Scott Borhauer is the founder and principal advisor of Smart Life Financial, where he designs retirement income, tax, and estate strategies for federal employees, business owners, and pre-retirees. His work centers on the arithmetic most people never get shown — Roth conversion sequencing, Social Security timing, and the tax cost of doing nothing — and he coordinates with CPAs and estate attorneys to execute the plan, not just write it. Licensed insurance producer, NPN 20016169.
Retirement Income Planning Worksheet
Step-by-step worksheet to map out your income streams and find gaps in your plan.
📊 Free instant download · Unsubscribe anytime
Related Posts
You Asked About a Roth Conversion. The Answer Might Be an Income Plan.
The call usually starts the same way — someone read about Roth conversions and calls saying they need one. Sometimes they're right. A fair number of times, the answer is an income plan, and the order is where the money is.
The Other Social Security Cut: The Tax Torpedo Explained
Social Security's taxation thresholds haven't moved since 1984. Here's how a $1,000 IRA withdrawal can cost 40.7% when your bracket says 22% — and what to do.
How a Discount Conversion Actually Works
A discount conversion is a legitimate application of ordinary valuation principles to an unusual asset — and five pressure tests that separate the real thing from the way it is often marketed.